EPF Wage Limit ₹ 15,000 to ₹25,000: What’s Approved and What’s Still Pending (2026)
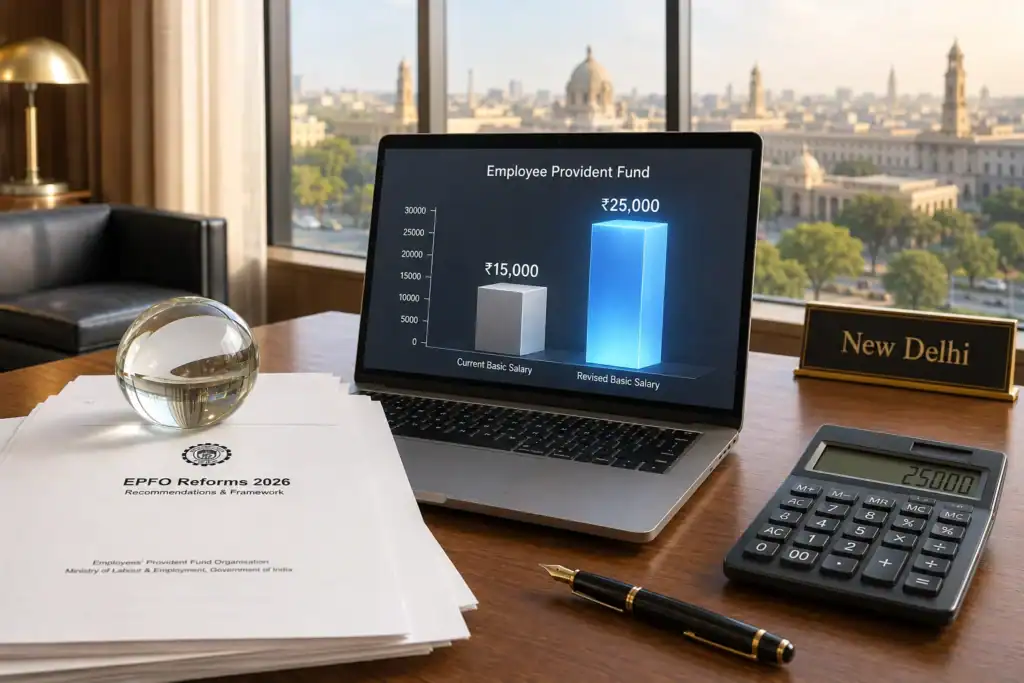
Understanding the PF Ceiling Limit for 2026: Navigating the ₹25,000 EPF Wage Shift
If you’ve looked at your salary slip in 2026 and felt like something was off, you’re not imagining it. There’s a major shift underway in India’s provident fund system, one that could quietly change how much lands in your bank account every month, and how much waits for you years down the line. Herein comes the issue of the increase of EPF wage limit from ₹ 15,000 to ₹25,000.
For over a decade, the EPF wage ceiling has sat at ₹15,000. It became the norm. Payroll systems adjusted to it. HR teams stopped thinking about it. Most employees barely noticed it.
But 2026 cracked that old number open. Now that the Union Cabinet has approved a revised wage ceiling, the new PF ceiling limit for 2026 is not something the Indian workforce can afford to ignore.
The government has approved a revised EPF wage ceiling of ₹25,000, a change that, on paper, might look like just another compliance update. In reality? It touches almost everything: monthly deductions, employer contributions, pension eligibility, tax planning, and even long-term retirement math.
And this isn’t just relevant for finance teams or payroll managers. If you’re a salaried employee in India, whether you’re early in your career, somewhere in the middle, or planning retirement, this shift matters.
Here’s what’s changing, why it’s happening now, the legal background behind it, and how it could hit your money in practical terms. No jargon for the sake of jargon, just the numbers, the rules, and what they actually mean in real life.
That queasy feeling on payday is not in your head. Something in India’s provident fund system is genuinely shifting, quietly enough that a lot of employees have not clocked it yet.
At a Glance: EPF Wage Limit ₹ 15,000 to ₹25,000
- The Threshold Hike: The Union Cabinet has approved raising the statutory EPF wage ceiling from ₹15,000 to ₹25,000, the first major adjustment since September 2014, pending official gazette notification.
- Take-Home Impact: For employees earning above the old limit, the mandatory monthly deduction rises from ₹1,800 to ₹3,000, meaning ₹1,200 less in hand every month unless employers restructure compensation.
- Pension Potential: The shift widens the EPS pensionable salary base, which can raise the maximum monthly pension by up to 60% at retirement for long-serving employees.
- Opt-Out Eligibility: Employees joining a new establishment with a basic salary above the ₹25,000 threshold qualify as “excluded employees” and can opt out entirely. Existing members cannot exit the system.
- Employer Costs: Organizations face higher payroll burdens due to increased employer matching, alongside higher EDLI and administrative charges calculated on the expanded wage base.
The Core Facts: What Is the Current EPF Wage Ceiling?
Before getting into what’s changing, it helps to know what this wage ceiling actually does, and why such a boring-looking number has such an outsized impact on retirement savings in India.
Under the Employees’ Provident Fund and Miscellaneous Provisions Act, 1952, any establishment employing 20 or more workers has to enrol its eligible employees in the EPF scheme. Employer and employee each put in 12% of the employee’s basic wages every month.
Sounds simple enough. But there’s a catch: that contribution isn’t calculated on your full salary indefinitely. It’s subject to a statutory wage ceiling, a cap that decides how much of your salary is considered for mandatory EPF contributions.
As things stand today, that ceiling remains ₹15,000 per month.
The ₹15,000 Legacy (2014 to Present)
That ₹15,000 limit has been around since September 2014, when the government raised it from the earlier ₹6,500 ceiling.
Back then, it made sense. Wages looked different. Inflation was lower. Salary structures across sectors were nowhere near where they are today.
The EPFO today manages retirement savings for more than 60 million active subscribers, making it one of the largest retirement fund institutions anywhere in the world. That’s not a niche policy issue. That’s the financial backbone of a huge slice of India’s workforce.
Here’s what the ceiling means in practice:
If your basic salary is ₹15,000, or even ₹50,000, your statutory EPF contribution is still calculated only on ₹15,000.
So:
12% × ₹15,000 = ₹1,800 per month.
That’s the mandatory employee contribution. Your employer’s matching obligation also stops there.
Anything above ₹15,000? Not automatically included.
Yes, employees can voluntarily contribute more through VPF. But unless the employer chooses otherwise, their mandatory contribution doesn’t rise beyond that ceiling.
And that’s where things start to feel outdated.
A worker earning ₹30,000, ₹50,000, or even more in basic wages may still be saving for retirement against a wage benchmark set over ten years ago. Over time, that gap grows, quietly but by a lot.
The Supreme Court Intervention (January 2026 Directive)
Interestingly, the real push for change didn’t come from payroll software companies, HR associations, or industry lobbying.
It came from the judiciary. In January 2026, the Supreme Court of India directed the Employees’ Provident Fund Organisation to revisit the ₹15,000 wage ceiling, effectively signalling that the existing cap may no longer reflect present-day wage realities.
The Court’s direction put real pressure on the EPFO and the government to come up with an updated wage ceiling.
And that matters.
Because once a policy question moves from “under consideration” to “under judicial scrutiny,” things tend to accelerate.
Since that directive, policy circles and industry bodies have been talking through what the revised ceiling should look like. Some estimates put the number somewhere between ₹21,000 and ₹30,000.
But right now, ₹25,000 appears to be the number gaining the most traction.
The Proposed 2026 Hike: Moving the Goalposts to ₹25,000
After years of silence around the EPF wage ceiling, things are finally starting to move, and this time, not by a few hundred rupees.
The number currently being discussed most seriously inside policy circles is ₹25,000. This proposed PF ceiling limit for 2026 isn’t an arbitrary jump; it’s an inflationary correction long overdue.
Nothing has been formally gazetted yet. That part matters. But by now, enough signals have emerged from government conversations, industry discussions, and labour-policy reporting to make one thing fairly clear: the ₹15,000 era is nearing its end.
And honestly, it was starting to feel overdue.
For employees, this isn’t just another bureaucratic revision buried in a government PDF. A higher ceiling changes the amount deducted from salary, increases employer contributions, affects pension calculations, and alters long-term retirement accumulation in ways many people haven’t fully processed yet.
So why ₹25,000? Why now?
Status Check: Has the ₹25,000 Ceiling Actually Been Approved? (Updated September 2026)
Short answer: yes, as of today. On September 16, 2026, the Union Cabinet approved raising the wage ceiling from ₹15,000 to ₹25,000. But approval isn’t the same as implementation, and the statutory ceiling in force right now is still ₹15,000.
That’s worth saying plainly, because the paper trail since this piece first went up has gotten a little confusing. Around May 29, 2026, the Ministry of Labour and Employment issued gazette notification S.O. 2702(E), giving the ₹15,000 ceiling formal standing under the Code on Social Security, 2020. It didn’t raise the number; it just carried the existing threshold into the new code. KPMG’s compliance alert on the notification confirms as much. The Union Budget earlier in 2026 left the figure untouched too.
Then in early August the story moved. Multiple outlets, citing an original Moneycontrol report, said the Finance Ministry’s Department of Expenditure had internally cleared a proposal to raise the ceiling to ₹25,000 and sent it to the Union Cabinet for sign-off. EPFO had reportedly pushed for ₹30,000 before the number settled at ₹25,000. Business Today’s coverage lays out that sequence, including the widely reported but still unconfirmed April 1, 2027 target date.
That changed on September 16, 2026, when the Union Cabinet, chaired by Prime Minister Narendra Modi, approved the Ministry of Labour & Employment’s proposal to raise the ceiling to ₹25,000, according to the official press release. The government says the move will bring more than 51 lakh additional employees within mandatory EPFO coverage. The proposal had already been recommended by the Expenditure Finance Committee at a meeting held on June 16, 2026. The annual government outgo is estimated at about ₹11,339 crore, against roughly ₹10,250 crore currently budgeted for it, with the five-year cost pegged at approximately ₹56,696 crore. What’s still missing is the gazette notification that actually brings the ₹25,000 figure into force, along with a confirmed effective date.
So where does that leave things? The ₹25,000 figure has now cleared its biggest political hurdle, but it still isn’t law. Payroll teams have nothing to act on yet. If your basic salary crosses ₹15,000 today, your mandatory EPF contribution is still calculated on ₹15,000. That changes the day the gazette notification says so, not before.
Why the Shift from ₹15k to ₹25k? (Inflation and Real Wages)
A lot has changed since 2014. Back when the EPF wage ceiling was raised to ₹15,000, that amount reflected a very different wage environment. Rent was lower. Grocery bills looked different. Fuel prices, well, you remember.
Twelve years later, that same number doesn’t stretch nearly as far. Between 2014 and 2026, India’s Consumer Price Index (CPI) has climbed sharply. In practical terms, ₹15,000 in 2014 doesn’t buy what ₹15,000 buys today, not even close.
If the EPF ceiling had simply kept pace with inflation, estimates suggest it would now sit somewhere between ₹24,000 and ₹26,000. Which makes the proposed ₹25,000 figure feel less like a policy experiment and more like a delayed correction.
Reports in the mainstream media say average salaries across organised sectors now sit well above the current ₹15,000 benchmark in most parts of India.
That creates a strange mismatch. Millions of employees earn well above ₹15,000 in basic wages, yet their EPF contributions are still being calculated using a salary ceiling designed for a completely different economic climate.
Raising the ceiling to ₹25,000 would pull a large portion of those employees back into fuller mandatory coverage, especially workers sitting in that ₹15,000 to ₹25,000 salary band who have effectively been living in a policy grey zone.
Other reports suggest the government also sees this as part of a wider push to strengthen long-term social security under India’s ongoing labour reforms. Short-term deductions may rise. That’s the uncomfortable part. But over a 20- or 30-year career? The retirement difference could be substantial.
Labour Codes vs. EPF: Addressing the ₹21,000 ESI Confusion
If you’ve spent any time discussing payroll changes with colleagues or honestly, even with some HR teams, you’ve probably heard the ₹21,000 number thrown around.
And that’s where confusion starts. A lot of people assume ₹21,000 is somehow connected to EPF. It isn’t.
That number belongs to ESIC, the Employees’ State Insurance Corporation scheme.
ESIC mainly covers health-related benefits: medical care, sickness benefit, maternity benefit, and disability cover. Right now, ESIC generally applies to employees earning up to ₹21,000 a month.
EPF is different. EPF is retirement-focused. Different legislation. Different deductions. Different purpose.
So:
- ₹21,000 = ESIC wage ceiling
- ₹15,000 = Current EPF wage ceiling
- ₹25,000 = Proposed EPF wage ceiling for 2026
Simple on paper. Confusing in real payroll conversations.
For a closer look at how ESI and EPF applicability differ, see this guide. Now add labour codes to the mix, and things get even messier.
India’s Code on Social Security, 2020 aims to bring multiple social security laws under one wider structure. In theory, that could eventually bring EPF and ESIC closer together. But theory and implementation are two different things. This piece notes that the labour codes are still being rolled out state by state and are not yet fully in force nationwide.
Which means, for now, the EPF Act of 1952 remains the law that actually governs provident fund contributions. So yes, the ₹21,000 and ₹25,000 numbers may appear in the same payroll conversation. But they’re solving completely different problems.
Financial Mechanics: How the New Ceiling Impacts Your Salary
This is the part most people actually care about. Policy debates are one thing. Court directives, labour codes, government proposals, all of that matters. But for most salaried employees, the real question usually comes down to something much simpler:
What happens to your salary?
If the EPF wage ceiling moves from ₹15,000 to ₹25,000, you’ll see it on your next payslip. The calculation base itself is shifting too. Under Section 2(y) of the Code on Wages, 2019, excluded allowances such as HRA and special allowances cannot exceed 50% of total remuneration. If they do, the excess gets added back to the basic wage, so the new 12% PF deduction gets calculated on a much wider wage base, up to the ₹25,000 ceiling.
For others, especially those who track every deduction, it could be the first number their eyes go to. So let’s break down the actual math.
The Formula: Calculating 12% on ₹25,000 vs. ₹15,000
EPF calculations are fairly straightforward once you see how the contribution gets split, but this is exactly where many employees get confused.
Under EPF rules, both employee and employer contribute 12% of Basic Salary plus Dearness Allowance, subject to the statutory wage ceiling.
From the employer’s 12% contribution:
- 3.67% goes to EPF
- 8.33% goes to EPS (Employee Pension Scheme)
Under the current ₹15,000 ceiling, contributions are capped there, even if your actual basic salary is much higher.
That means:
Current Ceiling (₹15,000)
Employee contribution: 12% × ₹15,000 = ₹1,800/month
Employer contribution:
- EPF portion = ₹550.50/month
- EPS portion = ₹1,249.50/month
Total monthly flow into your PF account: ₹3,600
Now set that against the proposed ₹25,000 ceiling. The math below shows how the PF ceiling limit for 2026 changes your monthly contribution:
Proposed Ceiling (₹25,000)
Employee contribution: 12% × ₹25,000 = ₹3,000/month
Employer contribution:
- EPF portion = ₹917.50/month
- EPS portion = ₹2,082.50/month
Total monthly flow: ₹6,000
That’s an increase of ₹2,400 every month.
Not small, not theoretical: actual money moving into long-term retirement savings.
Here’s how the two stack up, side by side:
| Component | Current (₹15,000 ceiling) | Proposed (₹25,000 ceiling) | Change |
| Employee EPF Contribution | ₹1,800/month | ₹3,000/month | +₹1,200/month |
| Employer EPF Contribution (3.67%) | ₹550.50/month | ₹917.50/month | +₹367/month |
| Employer EPS Contribution (8.33%) | ₹1,249.50/month | ₹2,082.50/month | +₹832/month |
| Total monthly flow into PF ecosystem | ₹3,600/month | ₹6,000/month | +₹2,400/month |
| Annual accumulation (combined) | ₹43,200/year | ₹72,000/year | +₹28,800/year |
And this is where things get interesting.
An extra ₹2,400 a month may not feel life-changing on its own. But retirement planning rarely works in monthly snapshots. It works through compounding.
At EPFO’s current long-term interest rate of 8.25% a year, the long-term difference gets a lot harder to ignore.
Illustrative 30-year corpus projection:
| Ceiling | Monthly Combined Contribution | Approx. 30-Year Corpus |
| ₹15,000 | ₹3,600 | ~₹58.5 lakhs |
| ₹25,000 | ₹6,000 | ~₹97.5 lakhs |
| Gain | N/A | ~₹39 lakhs |
That’s nearly ₹39 lakhs of additional retirement accumulation, driven largely by a single ceiling revision. Of course, real life rarely follows perfect spreadsheets. Salaries increase. People switch jobs. Interest rates change. Careers take detours.
Still, the larger point doesn’t change. A higher EPF ceiling doesn’t just increase monthly deductions. Over time, it can reshape what retirement actually looks like.
PF Deduction by Salary: What Different Pay Levels Actually Look Like
Most of the “how much PF comes out of my salary” questions people type into Google assume the deduction scales with their pay. Under the current ₹15,000 ceiling, it mostly doesn’t.
Here’s the rule in one line. Below ₹15,000 basic, your PF contribution is 12% of whatever you actually earn. At or above ₹15,000, it’s 12% of ₹15,000, full stop, regardless of whether your basic is ₹16,000 or ₹1,60,000.
| Basic Salary | Employee PF Deduction (Current ₹15,000 Ceiling) |
| ₹10,000 | ₹1,200 |
| ₹13,000 | ₹1,560 |
| ₹15,000 | ₹1,800 |
| ₹18,000 | ₹1,800 (capped) |
| ₹20,000 | ₹1,800 (capped) |
| ₹21,000 | ₹1,800 (capped) |
| ₹25,000 | ₹1,800 (capped) |
| ₹30,000 | ₹1,800 (capped) |
| ₹40,000 | ₹1,800 (capped) |
Notice what happens past ₹15,000. The number doesn’t move. Someone on ₹18,000 and someone on ₹40,000 are contributing exactly the same ₹1,800 a month, because the law only counts the first ₹15,000 of anyone’s basic wage.
That flat line is also exactly what the ₹25,000 proposal would redraw. Once the ceiling shifts, the cap point shifts with it. Basic salaries up to ₹25,000 would see their deduction rise step by step with pay, and the flat ₹1,800 line would reappear further out, at ₹3,000, for everyone earning ₹25,000 and above. You can find the full math for that further up.
One more wrinkle worth knowing. An employee can voluntarily contribute more than the statutory minimum through VPF, and the employer’s matching share can, in principle, follow. But the employer isn’t obligated to match anything past the statutory ceiling unless both sides agree to it in writing, per EPFO’s own guidance.
The Take-Home Pay Hit: Short-Term Pain, Long-Term Gain
Now for the part most employees actually care about first:
Will your in-hand salary drop?
In many cases, yes. And there’s no point pretending otherwise. Let’s say your basic salary is ₹25,000. Under the current ceiling, your employee EPF deduction is ₹1,800 per month. Under the proposed ceiling, that becomes ₹3,000. That’s an extra ₹1,200 deducted from your monthly salary Or ₹14,400 per year.
If your company doesn’t restructure your compensation, that money comes straight out of your take-home pay. That’s the short-term hit. But there’s another side to this.
EPF contributions remain eligible for tax deduction under Section 80C under the old tax regime. So if you fall in a higher tax bracket, part of that extra contribution may come back indirectly through lower taxable income. For example:
An employee in the 30% tax bracket contributing an extra ₹14,400 annually could save roughly ₹4,320 in taxes. Not enough to erase the impact completely, but enough to soften it. This guide notes that the 2026 tax rules have largely kept existing EPF tax treatment in place:
- Employee contributions remain eligible under 80C (old regime)
- Employer contributions up to statutory limits stay tax-friendly
- Withdrawals after 5 years of continuous service remain tax-free
For wider income tax changes affecting salaried employees, see this guide. So yes, cash in hand may shrink. But retirement security gets stronger. And for some people, that trade-off is worth it. For others, maybe not. Especially if monthly liquidity is already tight. That’s where salary structure starts to matter.
Will your employer reduce my in-hand salary?
This is probably the question HR teams are hearing most right now. And the answer is frustratingly simple:
It depends on how your compensation is structured.
Here’s how it usually plays out:
Scenario A: Fixed Gross Salary
If your offer letter says you earn a fixed monthly gross salary, say ₹50,000, then higher EPF deductions usually mean lower take-home pay.
Your employer isn’t automatically required to increase your gross salary to offset the deduction.
So yes, your in-hand salary could fall.
Scenario B: Fixed CTC Model
If your company uses a Cost to Company structure, things get trickier. Because your employer’s EPF contribution often forms part of your CTC. So if their contribution rises, they may adjust other salary components to keep the total CTC unchanged. Result? Your cash payout could shrink, even if your official salary package stays exactly the same. A little corporate math. Very common.
Scenario C: Employer Absorbs the Cost
Some larger companies may choose to absorb the extra contribution themselves.
That means:
- Your take-home pay stays largely unchanged
- Your employer increases the total compensation cost instead
Not every company will do this. But some will, especially in competitive hiring sectors. This report says many employers are expected to wait for the final government notification before making any pay changes. So, for now, there’s a lot of watching, modelling, and quiet spreadsheet panic happening inside payroll teams.
The Employer Perspective: CTC Restructuring and Compliance Costs
For employees, the proposed EPF ceiling hike usually starts with one question: “How much less am I taking home?” For employers, the question is very different: “How much more is this going to cost us, and how fast do we need to adapt?” And honestly, that’s where the real operational pressure begins.
A jump from ₹15,000 to ₹25,000 may sound manageable when you’re thinking about one employee. But multiply that across hundreds, or thousands, of workers, and suddenly finance teams are looking at a very different payroll bill.
This isn’t just about higher provident fund contributions either. It affects insurance contributions, administrative charges, payroll software settings, compliance filings, employee communication the whole machinery.
And if your organisation still runs salary structures built around older compliance assumptions, things can get messy fast.
Increased Employer Matching and EDLI Contributions
When most people think of employer PF contributions, they think of the employer’s 12% match. Fair enough, but that’s only part of the picture.
Under EPF rules, employers also contribute toward EDLI, the Employees’ Deposit Linked Insurance scheme, which gives EPF members a life insurance cover linked to their employment.
The EDLI contribution is currently calculated at 0.5% of wages, subject to the statutory ceiling. So, under today’s ₹15,000 ceiling:
Employer EDLI contribution:
0.5% × ₹15,000 = ₹75 per employee per month
Simple enough.
Now apply the proposed ₹25,000 ceiling:
0.5% × ₹25,000 = ₹125 per employee per month
That’s ₹50 extra per employee, every month.
On its own? Doesn’t sound dramatic.
But scale changes everything.
A company with 1,000 employees covered under this ceiling would see:
₹50 × 1,000 = ₹50,000 extra every month Just from EDLI.
And that’s before factoring in higher EPF, EPS, and admin charges.
Employers also pay administrative charges to EPFO, currently calculated at 0.5% of wages.
Which means:
- At ₹15,000 ceiling → ₹75/month
- At ₹25,000 ceiling → ₹125/month
Again, another ₹50 increase per employee.
Now combine the cascading statutory costs:
- Higher employer EPF contributions
- Higher EPS diversions
- Increased administrative charges
- Elevated liabilities under the Employees’ Deposit Linked Insurance (EDLI) Scheme, 1976: Because the EDLI premium mandates a 0.5% employer contribution mapped directly to the wage ceiling, raising the cap to ₹25,000 proportionally increases the employer’s insurance outlay while simultaneously enhancing the maximum statutory death benefit cover for the workforce
And suddenly, for mid-sized or large organisations, payroll costs start climbing by several lakhs every month.
That’s why finance teams aren’t treating this as a routine update.
How to Update Payroll Systems for the New Ceiling
Once the government formally notifies the new ceiling, HR and payroll teams won’t have much breathing room. Because statutory changes like this don’t just live in policy memos, they hit real salary cycles.
Miss a payroll update, and suddenly employees start flooding inboxes asking why deductions look wrong. So what actually needs to happen?
Here’s the typical compliance checklist:
Update the statutory ceiling inside payroll software
Sounds obvious. Still gets missed. Every payroll engine, whether it’s SAP, Zoho Payroll, Darwinbox, GreytHR, or a custom ERP, will need the ceiling changed from ₹15,000 to ₹25,000.
Many systems may push updates automatically. Still trusting automation blindly in payroll? Risky move. Manual verification matters.
Recalculate impacted employees
The biggest impact usually hits employees earning between ₹15,001 and ₹25,000 in basic wages.
This group often sees the sharpest change in both:
- Employee deductions
- Employer contributions
They’re the first batch payroll teams will need to audit carefully.
Review CTC structures
Some employers may choose to absorb the added cost. Others may restructure salaries to keep total CTC unchanged.
That could mean:
- Revised salary breakups
- Addendums to offer letters
- Fresh compensation communication
Not fun paperwork, but often unavoidable.
Update statutory filings
The Electronic Challan cum Return (ECR) on the EPFO Unified Portal will need updated wage and contribution data. Missed or incorrect filings can create compliance headaches later, sometimes months later, when reconciliation starts. And by then nobody remembers who changed what. Classic payroll problem.
Communicate with employees early
This part gets ignored far too often.
If salary deductions suddenly increase and nobody explains why, employees usually assume one of two things:
- Payroll made a mistake
- The company quietly cut take-home pay
Neither creates a healthy Monday morning.
A clear communication from HR, before the first revised payslip lands, can prevent a lot of confusion.
Review exempted PF trusts
Companies running their own exempted PF trusts need to bring internal trust rules in line with the revised statutory ceiling. That may require legal review, actuarial recalculations, or board approvals depending on the structure.
Definitely not something to leave for the last week of implementation. For official guidance, employers should monitor the EPFO Unified Portal, the EPFO FAQ page, and reform communications such as this one.
Because when a statutory change goes live, payroll doesn’t get grace periods. It just gets deadlines.
The EPS Pension Revolution: From ₹1,000 to ₹7,500?
When most employees think about EPF, they usually think about the provident fund balance, the lump sum they’ll eventually withdraw, maybe at retirement, maybe during a job transition, maybe for a home purchase somewhere in between.
Fair. But tucked inside the EPF system is another piece that often gets ignored until much later:
EPS, the Employees’ Pension Scheme.
And if the EPF wage ceiling really moves to ₹25,000, EPS may end up seeing one of the biggest ripple effects of all. In fact, for some employees, the pension impact could matter more than the PF balance itself.
That sounds dramatic. But once you look at the numbers, it starts making sense.
How a Higher Wage Ceiling Expands Pension Coverage
Under the current EPF structure, a part of your employer’s contribution doesn’t actually go into your provident fund.
Instead, 8.33% of the employer’s contribution is diverted into EPS.
But here’s the limitation:
That EPS contribution is capped based on the existing wage ceiling of ₹15,000.
So the maximum EPS contribution today works out to:
8.33% × ₹15,000 = ₹1,250 per month
That means even if your salary is a lot higher, your pensionable salary is still worked out using that ₹15,000 ceiling.
And that ceiling hasn’t moved since 2014.
That’s a long time in wage terms.
Now imagine the ceiling shifts to ₹25,000.
Suddenly the math changes:
8.33% × ₹25,000 = ₹2,082.50 per month
That’s an increase of more than ₹800 per employee, every month, flowing toward pension contributions.
It happens quietly and automatically, without the employee doing anything extra.
And over decades? That’s not small.
EPS pensions are calculated using this formula:
Monthly Pension = (Pensionable Salary × Pensionable Service) ÷ 70
For employees who complete long service periods, that formula becomes very meaningful.
For example:
An employee with 35 years of pensionable service under the current ceiling:
(₹15,000 × 35) ÷ 70 = ₹7,500/month
Under the proposed ₹25,000 ceiling:
(₹25,000 × 35) ÷ 70 = ₹12,500/month
That’s a 67% increase in the maximum pension potential.
Not a cosmetic policy tweak.
A real retirement difference.
For official EPS calculation guidance, see here.
And for workers nearing retirement age, this may be one of the biggest numbers in the entire reform package.
The Minimum Pension Hike Debate
While contribution ceilings are getting attention, there’s another conversation running alongside it, one that’s far more emotional for pensioners.
The minimum EPS pension.
Right now, many EPS pensioners receive just ₹1,000 per month.
Read that again.
₹1,000.
Even in 2014, people argued it wasn’t enough.
In 2026? For many retirees, it barely covers a utility bill.
Which is why pensioner associations, labour unions, and worker advocacy groups have been pushing hard for a revised minimum pension of ₹7,500 per month.
And the momentum keeps growing.
This guide says demands for a higher EPS pension floor have gained real traction in 2026, with several policy discussions and parliamentary recommendations keeping the issue alive.
That doesn’t mean approval is guaranteed.
Far from it.
Because raising the minimum pension comes with a direct fiscal cost for the government, which already funds the EPS system through budgetary subsidies.
And once pension commitments rise, they don’t quietly shrink later.
So while the demand for ₹7,500 is gaining visibility, the Ministry of Labour hasn’t formally locked in a number yet.
Still, if the wage ceiling moves higher first, it creates the financial and policy foundation for a future pension revision.
Which may be exactly where this is headed.
For pension eligibility details and related application processes, see this..
How much EPS pension will I get after 10 years?
This is one of the most searched EPS questions, and understandably so.
Under EPS rules, 10 years of pensionable service is the minimum threshold to qualify for monthly pension benefits.
So, let’s say an employee completes exactly 10 years under the proposed ₹25,000 ceiling.
The pension formula becomes:
(₹25,000 × 10) ÷ 70 = ₹3,571/month
Now set that against the current ceiling:
(₹15,000 × 10) ÷ 70 = ₹2,143/month
That’s a monthly increase of:
₹1,428
Maybe that doesn’t sound life-changing at first glance.
But retirement math is funny.
Stretch that over 20 years of retirement:
₹1,428 × 12 × 20 = roughly ₹3.43 lakhs
And that’s money the employee didn’t actively invest, trade, or manage.
It simply comes from being inside the system longer, and under a higher pensionable salary cap.
That’s why this reform matters more than many people realise.
Also worth remembering:
If an employee leaves service before completing 10 years, they typically don’t qualify for a monthly EPS pension. Instead, they may receive a withdrawal benefit, calculated under EPS rules.
And yes, the higher ceiling makes that number bigger too.
Quietly. But meaningfully.
Strategic Opt-Outs: Can You Avoid the EPF Deduction?
Once employees hear that PF deductions could rise under the new ₹25,000 ceiling, the next question usually comes fast:
“Can I just opt out?”
And honestly… it’s not a bad question.
Not everyone sees EPF the same way.
Some people love the forced discipline. Money goes in, compounds quietly, and one day it becomes a decent retirement cushion.
Others, especially higher earners, see it differently. They’d rather keep more liquidity, invest in equity funds, build their own retirement corpus, maybe chase better returns elsewhere.
So where does the law stand?
Can you actually avoid EPF if the ceiling moves to ₹25,000?
The answer is yes… but only in very specific situations.
And once you’re inside the system, getting out is a whole different story.
The ₹25,000 Threshold and Mandatory vs. Voluntary Coverage
Under current EPF rules, membership depends largely on your salary at the time you join employment, not what happens later.
That distinction matters more than most people realise.
As things stand today:
If your basic salary is ₹15,000 or below at the time of joining an EPF-covered establishment, EPF membership is generally mandatory.
If your salary exceeds the wage ceiling at the time of joining, you may qualify as an “excluded employee” and can choose not to join.
Now if the ceiling officially moves to ₹25,000, that threshold rises too.
Meaning:
Employees joining a new EPF-covered company with a basic salary above ₹25,000 may have the option to remain outside the EPF system.
That’s where strategic decisions start creeping in.
Some employees may choose to opt out and invest that money elsewhere.
Others may still join voluntarily because, frankly, walking away from an employer match often feels like leaving money on the table.
And there’s another catch people often miss:
Once you become an EPF member, you generally cannot simply exit later while continuing employment in a covered establishment.
Salary increases don’t automatically remove you.
Promotions don’t remove you.
Crossing the ceiling doesn’t remove you.
Once you’re in… you’re usually in.
This piece explains that employees earning above the statutory ceiling at the time of joining may have a choice about EPF membership, but that choice is usually locked in for the rest of that job.
Which makes the joining decision a bigger deal than many employees realise.
Who Actually Has to Register for EPF? The Establishment-Size Rule
Salary isn’t the only gate here. Before an individual’s wage ceiling status even matters, the employer has to be covered in the first place.
Under Section 1(3) of the EPF Act, coverage is mandatory for any factory in a specified industry employing 20 or more people, and for any other establishment employing 20 or more people that the central government has separately notified. In practice, that second category has grown wide over the decades. Most offices, shops, and service businesses of any real size fall under it.
Twenty is the number that matters, not twenty-five, not fifty. Once a company crosses it, at any point during the year, registration stops being optional.
What about smaller businesses? They’re not locked out. Section 1(4) lets any establishment with fewer than 20 employees opt into EPF voluntarily, provided the employer and a majority of the staff agree to it. Some small firms do this deliberately, usually because they want to offer retirement benefits to attract talent without waiting to hit the headcount threshold. The statutory text for both provisions sits here, straight from EPFO.
So the fuller picture of “do I have PF” actually runs through two separate filters. First, does your employer meet the coverage threshold, mandatory at 20-plus, optional below it. Second, assuming they’re covered, does your salary put you inside mandatory individual coverage or into excluded-employee territory, which is what the rest of this section already walks through.
Miss the first filter and the second one never comes into play. It’s a detail payroll teams know cold and employees almost never think about, until someone at a 15-person startup asks why there’s no PF line on their payslip.
Understanding Section 26(6) of the EPF Act
This is where the law gets a little more technical.
Section 26(6) of the Employees’ Provident Funds and Miscellaneous Provisions Act, 1952 governs voluntary EPF membership for employees who would otherwise fall outside mandatory coverage.
In simple terms:
If your salary exceeds the wage ceiling and you qualify as an excluded employee, you can still choose to join EPF, provided your employer agrees.
That’s what Section 26(6) allows.
So an employee earning above ₹25,000 under the proposed ceiling could still voluntarily participate in EPF.
Why would someone do that?
A few reasons:
- Employer matching contributions
- Stable, government-backed returns
- Tax advantages
- Long-term retirement discipline
Not flashy benefits. But powerful over time.
There’s also the pension angle.
If you voluntarily contribute on higher wages, your EPF contributions may rise, but your EPS pensionable salary may still remain subject to the statutory ceiling unless additional higher pension options apply.
And that’s where things stop being simple.
Especially after the Supreme Court’s November 2022 higher pension judgment and the EPFO circulars that followed.
Employees who contributed on higher salaries before September 2014 may have rights or options that newer members don’t automatically have.
It’s one of those areas where the law, payroll practice, and litigation history all intersect.
Messy. But it matters.
For updated circulars and notifications on this subject, see here .
What happens if my basic salary crosses the limit?
This one creates a lot of confusion.
Here’s the short version:
Nothing happens automatically.
If you’re already an EPF member and your basic salary later rises beyond ₹25,000…
You stay an EPF member.
You don’t get auto-exited.
You don’t suddenly become exempt.
You don’t get a refund or an opt-out form.
Your EPF membership continues.
Your contributions are typically calculated using the statutory ceiling (₹25,000, if the proposal becomes law), unless you and your employer choose to contribute on actual higher wages voluntarily.
So:
Salary goes up. Membership stays.
Simple.
Now if you’re not yet an EPF member, and you join a company with a basic salary above ₹25,000. That’s where the choice comes in. You may be able to decline EPF membership at joining. But before doing that, it’s worth thinking carefully. Because opting out doesn’t just reduce deductions.
It may also mean walking away from:
- Employer matching contributions
- Pension accumulation
- Tax-friendly retirement savings
Sometimes flexibility wins. Sometimes guaranteed compounding wins. Depends on the person. Depends on the stage of life. And honestly, that’s what makes this one of the most strategic decisions in the entire EPF conversation.
High Earners’ Dilemma: EPF vs. NPS in 2026
For employees earning well above the proposed ₹25,000 EPF ceiling, the conversation eventually shifts.
It stops being about mandatory deduction and starts becoming about strategy.
Because once your salary moves into higher brackets, ₹50,000 basic, ₹80,000, ₹1 lakh or more, the statutory EPF contribution becomes a fairly small slice of your income.
At that point, the real question isn’t:
“How much PF am I paying?”
It becomes:
“Where should the rest of my retirement money go?”
And in 2026, for a lot of salaried professionals, that decision usually comes down to two familiar options:
EPF (and optionally VPF) vs. NPS (National Pension System)
Both offer tax benefits. Both are designed for retirement. Both have loyal supporters.
But they work very differently once you get into the details.
And for high earners, those differences matter a lot.
Tax Efficiency: Section 80C vs. Section 80CCD(1B)
This is usually where people start weighing the two against each other.
Not returns. Not flexibility.
Taxes.
Fair enough.
Because for many salaried employees, tax efficiency is what pushes retirement planning from “I’ll do it later” to “Okay, let’s actually set this up.”
This guide (https://finright.in/blogs/epf-tax-changes-2026-key-budget-updates-explained) says the 2026 tax rules largely keep existing retirement tax benefits intact.
So, let’s break it down.
EPF (Under the Old Tax Regime)
EPF continues to offer what’s often called EEE treatment: Exempt, Exempt, Exempt.
Meaning:
- Contributions qualify for deduction under Section 80C (within the ₹1.5 lakh cap)
- Interest earned stays tax-friendly, subject to existing limits
- Withdrawals after 5 years of continuous service generally remain tax-free
Employer contributions up to statutory limits also continue to enjoy favorable tax treatment.
And if you contribute extra through VPF, that too generally falls within the same 80C umbrella.
Solid. Predictable. Familiar.
But there’s a limitation.
For most higher earners, the ₹1.5 lakh 80C limit gets exhausted fast.
PF, life insurance, ELSS, principal repayment, tuition fees… it all piles into the same bucket.
Which means extra EPF contributions don’t always create extra tax advantage.
NPS (National Pension System)
This is where NPS gets interesting.
NPS offers:
- Deduction under Section 80CCD(1), within the broader 80C limit
- Plus an additional ₹50,000 exclusive deduction under Section 80CCD(1B)
That second benefit is what grabs attention.
Because it sits outside the normal 80C cap.
Meaning even if your entire ₹1.5 lakh 80C bucket is already full, NPS still gives you another tax-saving window.
That’s a big deal for higher-income professionals.
At a 30% tax bracket, a ₹50,000 NPS contribution could save roughly ₹15,000 in taxes annually.
No complicated hacks. Just clean tax efficiency.
This report (https://kpmg.com/xx/en/our-insights/gms-flash-alert/2026/flash-alert-2026-051.html) notes the government has kept this structure in place for 2026, which makes NPS one of the more underused retirement tax tools for salaried employees.
And honestly, a lot of people still ignore it.
Fixed Returns (EPF) vs. Market-Linked Growth (NPS)
This is where numbers stop being purely tax-driven and start becoming personal.
Because EPF and NPS run on completely different philosophies.
EPF: Stability First
EPF is built for people who value predictability.
Its biggest strengths:
- Government-backed structure
- Historically stable returns (currently around 8.25%, as per EPFO)
- No market volatility
- Full capital protection
- Tax-friendly maturity
There’s also something quietly powerful about forced investing.
Money leaves your salary before you can spend it.
No temptation.
No timing the market.
No checking NAVs at midnight.
For many people, that discipline alone is what makes EPF work so well.
Especially in your 40s and 50s, when preserving capital often matters more than chasing aggressive growth.
NPS: Growth Potential
NPS plays a different game.
Instead of fixed declared returns, it gives exposure to:
- Equity markets
- Corporate bonds
- Government securities
That means:
More upside. More volatility. More uncertainty.
Historically, equity-heavy NPS allocations have delivered higher long-term returns than EPF in many periods, sometimes in the 12–14% range over long horizons.
But of course…
Markets don’t move in straight lines.
Some years feel brilliant.
Some years feel… less brilliant.
That’s the tradeoff.
NPS also comes with withdrawal restrictions:
- Up to 60% can typically be withdrawn as a lump sum at maturity (tax-friendly)
- The remaining 40% usually goes toward annuity purchase
So yes, you get growth potential.
But you also give up some flexibility.
So Which Makes More Sense in 2026?
For most high earners, it’s probably not an EPF or NPS decision.
It’s usually EPF and NPS.
That combination often works better than picking sides.
A practical pattern many financial planners lean toward:
If you’re under 35:
You probably have time on your side.
That often makes NPS, especially equity-oriented allocation, more attractive alongside mandatory EPF.
You can afford volatility.
You can recover from bad market years.
You can let compounding do its thing.
If you’re above 50:
The equation changes.
Retirement gets closer.
Capital protection starts feeling less theoretical and more real.
That’s where EPF’s stability often becomes more valuable.
Less excitement.
More predictability.
Sometimes boring wins.
There’s also another layer to watch in 2026.
The new labour code’s 50% wage rule, which requires at least half of total remuneration to qualify as wages for social security calculations, could independently increase EPF contributions for many employees.
That means some high earners may see PF contributions rise from two directions at once:
- Higher wage ceiling
- Higher wage base
This piece discusses how the combined impact could meaningfully alter salary structuring across sectors.
And for employees also juggling professional tax obligations across states, this reference is worth keeping handy:
Because at higher income levels, retirement planning is rarely about just one deduction.
It’s about how the whole system fits together.
Messy spreadsheets and all.
Frequently Asked Questions: EPF Wage Limit ₹ 15,000 to ₹25,000
The Union Cabinet has approved raising the statutory EPF wage ceiling from ₹15,000 to ₹25,000. This means mandatory 12% provident fund deductions will soon be calculated on basic wages up to ₹25,000, increasing the maximum statutory employee contribution to ₹3,000 per month. The policy takes effect once the official gazette notification is published.
Yes, for most employees earning above the old threshold, take-home pay will drop. If your basic salary exceeds ₹15,000, your mandatory monthly deduction will increase by up to ₹1,200. Unless your employer restructures your Cost to Company (CTC) to absorb this compliance cost, this extra contribution comes directly out of your monthly in-hand salary, though it strictly builds your tax-friendly retirement corpus.
If you are joining a new company and your starting basic salary is above ₹25,000, you qualify as an “excluded employee” and can legally opt out of EPF before your first contribution. However, if you are already an active EPF member, you cannot exit the system, even if your salary crosses the new ₹25,000 limit. Employees choosing to contribute voluntarily on higher wages must submit a Section 26(6) joint declaration with their employer.
This ceiling hike dramatically impacts retirement planning. Because the employer’s 8.33% contribution to the Employee Pension Scheme (EPS) is strictly capped at the wage ceiling, shifting this limit to ₹25,000 widens your pensionable salary base. This adjustment can boost your maximum monthly EPS pension by up to 60% upon retirement.
PF Ceiling Impact Analysis
| Component | Current Scenario (₹15,000 Ceiling) | Proposed 2026 Scenario (₹25,000 Ceiling) | Change / Delta |
| Statutory Wage Ceiling | ₹15,000 | ₹25,000 | +₹10,000 |
| Employee Contribution (12%) | ₹1,800 | ₹3,000 | +₹1,200 |
| Employer EPF (3.67%) | ₹550.50 | ₹917.50 | +₹367.00 |
| Employer EPS (8.33%) | ₹1,249.50 | ₹2,082.50 | +₹833.00 |
| Total Monthly Contribution | ₹3,600 | ₹6,000 | +₹2,400 |
| Annual Accumulation | ₹43,200 | ₹72,000 | +₹28,800 |
| EDLI & Admin Charges (1%) | ₹150 (75+75) | ₹250 (125+125) | +₹100 |
| Estimated 30-Year Corpus* | ~₹58.5 Lakhs | ~₹97.5 Lakhs | +₹39 Lakhs |
*Assumes an illustrative 8.25% average interest rate and continuous service.
What You Should Do Right Now
The proposed jump from a ₹15,000 EPF wage ceiling to ₹25,000 isn’t just another compliance update buried in a policy circular.
If this gets formally notified, and all signs suggest that it eventually will, it could become one of the biggest shifts in India’s retirement savings rules in over a decade.
And like most financial policy changes, the impact won’t be evenly felt. For some employees, it’ll show up as a slightly smaller salary credit every month. For others, it could mean a much bigger retirement corpus, better pension potential, and a stronger long-term safety net.
For employers It means higher contribution costs, payroll restructuring, and compliance work that probably nobody was excited to inherit.
Still, whether you like the change or not, the direction seems pretty clear. India’s social security system is moving toward broader coverage, higher wage recognition, and stronger retirement contributions. The real question now isn’t whether the change matters. It’s whether you’re prepared before it lands.
For Employees
If you’re salaried, this is a good moment to stop treating PF as that deduction you glance at once a month and ignore.
Actually run the numbers.
Ask:
- How much will your monthly EPF deduction increase if the ceiling moves to ₹25,000?
- How much does that affect your take-home salary?
- If you’re under the old tax regime, how much of that gets offset through Section 80C tax savings?
- If you’re already maxing out 80C, should you start looking at NPS to use the additional ₹50,000 deduction under Section 80CCD(1B)?
And if retirement is less than 10 years away, don’t ignore the EPS side of this. That pension uplift may matter more than you think.
For HR and Payroll Teams
This is not something to react to after the notification hits your inbox. Preparation now saves chaos later.
Practical steps:
- Review whether your payroll platform is ready for a statutory ceiling change
- Identify employees in the ₹15,001–₹25,000 salary band, they’re likely to be affected first
- Model the employer cost impact across your workforce
- Prepare internal communication templates before revised payslips create confusion
- Audit existing CTC structures to see whether salary redesign becomes necessary
And keep watching the EPFO Unified Portal (https://unifiedportal-emp.epfindia.gov.in/epfo/) and Ministry of Labour notifications for the final gazette announcement.
Because when payroll changes hit, employees don’t usually wait quietly for explanations. They notice quickly.
For Employers (Strategic Planning)
If you’re running workforce planning or finance strategy, the ceiling hike shouldn’t be treated as just a payroll event. It’s a compensation strategy event.
Questions worth asking now:
- Will your organisation absorb the increased employer contribution, or restructure CTC?
- Do existing salary models still make sense under both the higher wage ceiling and potential labour code wage definitions?
- Does your current employee benefits strategy still hold up if EDLI and PF costs increase?
- Should voluntary retirement options like VPF or NPS education be offered more actively to employees?
And for companies managing large employee populations, even small per-head increases can quietly turn into major annual budget shifts.
A few hundred rupees per employee doesn’t sound like much. Until you multiply it by 2,000. Then finance notices very quickly.
The ₹25,000 EPF shift feels less like a new policy, and more like a correction that probably should have happened years ago. Its real effects won’t play out overnight. They’ll unfold gradually in salary slips, pension calculations, employer budgets, and retirement balances built over decades. Which means the smartest move right now isn’t panic. It’s preparation.
For ongoing updates and official guidance, keep an eye on the official EPFO website.
Disclaimer
This article is intended for informational purposes only and does not constitute financial or legal advice. Readers should consult a qualified financial advisor or legal professional for guidance specific to their situation. All figures relating to the ₹25,000 ceiling reflect the Union Cabinet’s approval as of September 16, 2026, and remain subject to the official gazette notification that will bring the change into force.

Discussion (7)
Leave a Reply